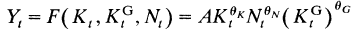Sabtu, 15 Oktober 2011

I mug pandas


Two things I don't understand. The first is why people think pandas are so unbearably cute. They're not bad, but I think they are out-cuted by most bears out there, including polar bears, brown bears, and maybe even black bears. Who's with me?

The second thing I don't understand is why opponents of attempts to "get tough" on China's currency policy - call them the Panda Knights - are comfortable with simplistic arguments and hand-waving dismissals. I realize that "free trade" is one of the few issues on which economists have allowed them to think they have a consensus over the past half-century. And I also realize that trade wars are scary in a geopolitical sense, regardless of the economics. But that is no reason to ignore the serious scholarly research that supports the idea of getting tough with China, or to assume that Congress' attempts to do so constitute political pandering.

One example of this sort of analysis is Michael Cohen's recent piece in Foreign Policy magazine, entitled "Panda Mugging." Here's the economic argument:
[A stronger yuan] would likely lead jobs to trickle to other low-wage countries rather than back to the United States -- a phenomenon that is already taking place as labor costs in China are on the rise.
There are theoretical reasons to believe that this is an oversimplification, and may just be flat-out wrong. Suppose the dollar appreciates against the yuan but not against the Indonesian rupiah, and that low-wage manufacturing jobs simply migrate from China to Indonesia. Suppose that the loss of those low-wage manufacturing jobs in China precisely cancels out the increased purchasing power of the stronger yuan, so that China's imports from the U.S. remain unchanged. But Indonesia will be richer, because it has gained jobs! And higher Indonesian incomes, at the same dollar/rupiah exchange rate, will mean Indonesia will buy more goods and services from the U.S., boosting our exports and creating jobs in the U.S. End result: Good for America, good for Indonesia (and neutral for China).

The lesson here is that trade-weighted exchange rates are what matter. And in fact, it may be the case that other export-dependent countries keep their own currencies artificially depressed to maintain competitiveness with China, even though this forces them to acquire crappy dollar assets as government reserves. If the yuan were to get stronger, these countries would also probably feel free to let their own currencies appreciate, lowering the cost of American exports all over the world, and creating even more jobs here.

This is not rocket science. Basic economics says that price controls are inefficient, and the yuan/dollar peg is the world's biggest price control.

But don't take my word for it. Some very smart people have done serious scholarly research in this area. Take Menzie Chinn (of Econbrowser fame), whose detailed statistical analyses conclude that a rise in the value of the yuan would be good for everyone involved. Or watch Paul Krugman, a lifelong trade economist, explain the intuition. These guys cannot be dismissed with a hand-wave or a shout of "protectionism".

Anyway, here is Michael Cohen's argument why the yuan bill, now stalled in Congress by the Republican House leadership, is mere political theater:
In a way, it's surprising that it took this long for Congress to get around to making China a scapegoat for the continued U.S. downturn. After all, finding a foreign bogeyman at a time of domestic economic dissatisfaction is hardly unusual. In the 1930s, it helped spur passage of the Smoot-Hawley tariffs; in the 1980s and early 1990s, economic fears -- and high-profile investments by Japanese businesses, like the purchase of Rockefeller Center -- led to a round of Japan-bashing in popular culture and the media... 
But for all the bipartisan panda-mugging going on, it's unclear that the American people are buying it quite yet. According to a recent poll by the Pew Research Center, when given an option of "getting tougher with China" or "building a stronger relationship," voters supported the latter by a 53-40 margin. Even though all but five members of the Senate Democratic caucus voted for this week's currency bill, only 32 percent of Democratic voters want to see a get-tough approach to China.

The seeming contradiction here - why would China-bashing be a good political strategy if it went against majority opinion? - implies that there is some narrow special-interest minority that is pushing both Democrats and Republicans toward a trade war. But who would that minority be? American manufacturing interests? Seems unlikely, given how much manufacturing has shrunk as a percentage of our economy during the past few decades. Unions? Ha. 

In fact, it seems to me that the special-interest groups that matter are lining up against the currency bill. U.S. multinationals made record profits in the 2000s as American incomes stagnated; this increase in the "capital share of income" was made possible by the dumping of a huge, capital-poor Chinese labor force onto the global markets, making workers less scarce and capital more scarce. But that effect was exaggerated by the yuan peg, which made Chinese labor even cheaper and American capital even more expensive. Thus, it is no surprise that multinationals are putting big pressure on John Boehner to keep the currency bill from reaching the House floor; up til now they have been receiving a bigger and bigger share of an American pie that is now shrinking, and a stronger yuan might remove that lifeline.

So I am not sure why opponents of a "get tough" China policy are so cavalier about the strength of their arguments. It's not that there are no good arguments against getting tough. After all, tariffs might not budge China from its mercantilist currency stance, and the resulting trade war might very well turn into a lose-lose for both sides. Getting tough is therefore risky. But I think that the valiant Panda Knights are a little too solicitous of their fuzzy friend when they claim that the yuan peg itself is no big deal, or that Congress is in the pocket of nefarious protectionist special interests.

Update: Ryan Avent takes me to task, writing:

Noah Smith seems to imply that critics of a "get tough" approach mainly think there would be no benefit to a yuan appreciation. I readily agree that there would be some benefit to both China and America of an appreciation in the yuan. It's difficult to demonstrate that there would be substantial benefit, however. Mr Smith cites economist Menzie Chinn in support of the point that a yuan appreciation would benefit both parties. Fair enough, but Mr Chinn has also written that a dearer yuan might not lead to a big increase in Chinese imports and might not have much of an effect in the absence of a broader Asian appreciation...There is a benefit there, but it's not at all sure to be a large one.
Ryan is right that Chinn definitely does hedge his bets. But, reading Chinn's post, I take away a very different message:

The fact that yuan revaluation would not necessarily have a large impact on job creation (for that we need vigorous and immediate expansionary monetary and fiscal policy) does not mean that it wouldn’t be a (very) good thing, however...[A]ccelerated yuan appreciation would be a good thing, in that it would facilitate global adjustment of current account balances, as well as the transition to a new development model for China. Paul Krugman has forcefully argued that accelerated yuan appreciation would help US employment, based on work by Autor, Dorn and Hanson (2011) (discussed in this post), and I'm willing to be convinced.
Chinn then goes on to link to a paper of his that finds that the Chinese trade balance does respond to exchange rates in the logical fashion.

Avent goes on to repeat the strongest Panda Knight argument, which is that trying to muscle China into changing their policy is a dangerous game. I've never disputed that. I'm only arguing that in their zeal to stop America from launching a trade war, Panda Knights often rely on hand-waving arguments. If and when the currency issue becomes the focus of increased public and intellectual attention - as it soon may if Mitt Romney wins the Republican nomination - their willingness to throw the kitchen sink at their opponents may not help the Panda Knights' credibility.

Update: Ryan's co-blogger gives a welcome reminder that yuan appreciation would be great for the vast majority of Chinese people, and it is only the narrow interests of well-connected exporters that keep this from happening. When you see the Panda Knights post pictures of poor sad pandas in cages, ostensibly supposed to represent China's suffering at the hands of the U.S., recall that the people benefiting most from the yuan peg are China's 1%, not its struggling hard-working masses.

Rational Expectations vs. Heliocentrism


More philosophy-of-science blogging...

It's not often that I take strong exception to a Matt Yglesias point, but today is one of those days. Discussing John Kay's epic rant against modern macro, Matt compares the Rational Expectations Revolution to the Copernican Revolution in astronomy:
The basic impulse to say that the theory has to make sense and be grounded in a compelling account of how the world works makes major contributions here. It’s why Copernicus ditching geo-centrism for heliocentrism, and it’s how Newton develops the theory of gravity. But the instinct to say that no, the important thing is for the theory to produce actual results is also important. If we’d stuck with Copernicus’s “theoretically compelling” idea about perfect circles, we’d never have noticed that this was actually a totally arbitrary modeling assumption with no basis whatsoever...What’s more, while in retrospect we see Copernicus as the ancestor of our modern way of thinking, the fact of the matter is that if you were trying to launch a rocket ship somewhere in the early 16th Century you’d be much better off chugging along with the epicycles rather than siding with the guy who knew that the earth orbited the sun. 
My view, with both all due respect and all due derision, is that the Robert Lucas types are like the early Copernicans here. There’s something admirable in their insistence that it ought to all work out to an easily modeled system grounded in compelling theoretically considerations. The New Keynesian model is a mess, like late-Ptolemaic astronomy, thrown together to account for observed reality. But you don’t fly to a moon with an elegant model that delivers mistaken predictions about where the moon’s going to be. And what we actually need is a Kepler to give us an elegant model that actually predicts the phenomena, and then a Newton who can explain what that model means.
While I agree with Matt's take on how good science works (alternating steps of theoretical deduction and experimental induction), and with his take on the Copernican Revolution, I think he's being way too generous with the analogy to Rational Expectations. For two reasons:

1. Unlike heliocentrism, we don't know yet that Rational Expectations is right. It is certainly not the case that Rational Expectations is the only "easily modeled system grounded in compelling theoretical considerations." There are plenty of alternatives! The obvious candidate here is a model where people learn over time. If you don't think that's a compelling alternative, just ask recent Nobel winner Thomas Sargent; even though he helped invent Rational Expectations, when found that the RE models didn't fit the data, he started working on learning-based models instead. So until the data give us a good idea of which overarching theoretical framework (if any) describes the world, we should treat RE as only one candidate among many. It may not even turn out to have been a good guess.

2. The Rational Expectations people didn't just insist that macroeconomists use self-consistent, perfectly microfounded Theories of Everything. In fact, they didn't stop at insisting that people use Rational Expectations! They went so far as to insist that theories of business cycles should be driven by so-called "real shocks" - changes in technology, changes in government policy, or changes in people's willingness to work. These were at the heart of Ed Prescott's "Real Business Cycle" theory, which became the heart of the "freshwater" school of macro. Although New Keynesian models also use the Rational Expectations framework, freshwater types went out of their way to denigrate these demand-based models. The current insistence by political conservatives that our economic malaise is due to workers' laziness, or "policy uncertainty," or uncontrollable changes in technological progress, is given intellectual heft by the freshwater school's insistence that these are the only things that should matter. It's kind of like if Copernicans had called Kepler a "bad guy" for daring to suggest elliptical heliocentric orbits instead of circular ones. 

I try not to be too hard on the Rational Expectations Revolution. It was motivated not only by theoretical elegance or ideology, but by observation of the real world - specifically, the failure of stimulative monetary policy in the 1970s. And it may well have erased a false sense of certainty among econometricians that was leading to policy mistakes (I plan to write a post about this soon). That is all to the good. But the revolution has not yet led to a theory of business cycles that fits the data well. And it very well may never do so - especially, I predict, if its adherents keep insisting on including only "real shocks" in their models. Until RE gives us something constructive, I think that comparisons with Copernicus are premature.

Update: Gregory Chow makes my first point...with real math and data!

Kamis, 13 Oktober 2011

Fire Prevention Week

This week is the National Fire Protection Association’s (NFPA) Fire Prevention Week.  This is a great chance for you and your family to discuss the danger of fire, the best ways to prevent fires in the home and create an escape plan if fire were to occur in your home.  The National Fire Protection Association has teamed up with Scholastic, Inc. and have made great educational programs for families.  Click the below hyper link and be directed to the NFPA’s website that focus on the educational materials.  The materials are free.

Senin, 10 Oktober 2011

Three cheers for Sargent & Sims, one and a half for the "Economics Nobel"


Today, as you may have heard, the Sveriges Riksbank Prize in Economic Sciences in Memory of Alfred Nobel, more commonly called the "Economics Nobel," went to Thomas Sargent and Chris Sims. To get some info about Sims' work, see here and here, and to get some info about Sargent's work, see here.

First, what I think about today's award (as if that matters, ha). Short version: I heartily approve.

Both of these guys are data guys - empiricists, first and foremost. Specifically, both are macro data guys, which means the difficulty of their job is somewhere between Moses and Gandalf. I have nothing but respect for anyone who manages to make any progress at all in macro empirics. And furthermore, I think that good empirics is exactly what macro needs right now; the field has had a wild proliferation of theories that describe anything and everything, with far too few efforts to prune the idea tree and isolate which of the models are really describing the world. Thus, both Sims and Sargent have, in my eyes, been fighting the good fight.

This applies to Sargent especially. Sargent is famous for "taking models seriously," i.e. testing econ models like you would test a model in physics or biology. As a result, although Sargent is typically identified with the "freshwater" or "rational expectations" school of thought, his hardheaded empiricism was actually somewhat of a thorn in the side of the original RBC guys (Lucas and Prescott), who went so far as to ask him to stop testing their models! Also, his most famous work indicated that central banks, which we usually task with stabilizing both GDP growth and inflation, might not be powerful enough to do even one of those. This is a splash of cold water for both Milton Friedman-era monetarists and for modern believers in central bank omnipotence.

So, basically, Sargent is a badass. Scientists who exert serious efforts trying to knock down their own schools of thought are usually unsung heroes, and it's good to see one of them getting recognition.

As for Chris Sims, I'm much more familiar with his work, having taken a time-series econometrics course from the eminent Lutz Killian of Michigan. Sims is best known as the inventor of the Vector Autoregression, a way of looking at data that makes as few theoretical assumptions as possible. I like this approach. VARs have fallen somewhat out of favor due to their enormous standard error bands; rare is the properly specified VAR that actually makes a strong conclusion about what the data says. But I see this as a feature, not a bug! All too often, macroeconomists claim "empirical support" from the flimsiest of hand-waving (e.g. "The correlation in the data is 1.45, my model gets 1.13, so that's pretty close."). VARs are honest about what they don't know. 

So basically, I think these are great awards. However, my longstanding dislike for the "Economics Nobel" itself remains. 

What people need to understand about the "Economics Nobel" is that it is not a prize for a specific discovery, like the science Nobels (medicine, physics, and chemistry). It is more of a lifetime achievement award, like the Fields Medal in mathematics. The reason this is so is that to get a science Nobel your discovery actually has to be verified empirically, while in economics, convincing empirical verification is extremely rare. So what ends up happening is that "Economics Nobels" are generally given either for A) development of new techniques and methods, or B) theories that tell interesting stories. 

I have no problem with the development of new techniques and methods (it would be pretty dumb if I did!), but I think it's obvious that it's a lower bar to clear, science-wise, then what medicine Nobelists face. In biology, a new technique that leads to no new empirically verified discoveries (or demonstrably useful technologies) is just not that interesting. In economics, DSGE models won Nobels long before there was any DSGE model capable of making good macroeconomic forecasts (some would argue there still is no such model). The prize committee just thought DSGE was neat.

It's not just the prize committee that makes the decisions, though; it's the profession itself. Consensus is key. But in a field with as little empirical verifiability as macreconomics, consensus is something of a free parameter, subject to fads and herd behavior. In 40 years the profession may have completely abandoned DSGE, but Ed Prescott's Nobel will stand forever. 

The shifting winds of consensus lead to the politicization of the economics award. This has been noted and criticized by prize recipients Gunnar Myrdal and Friedrich Hayek. The "Economics Nobel" confers a level of respect to the theories of the recipients that is almost on a level with that accorded by the science Nobels, but the decision process is sort of halfway between the science prizes and the Nobel in Literature. Like economics itself on its worse days, the prize is always in danger of putting a sheen of "science-y-ness" on matters of opinion.

This year, of course, the politics are fairly obvious, and I happen to agree with them completely. Macroeconomies all over the world are doing some really weird stuff. There are lots of ideas, but little consensus, about which theories we should be using to understand events like the financial crisis, Little Depression, and current relapse, not to mention globalization and China. In times like these, it is best to look to the data first. Pruning the idea tree is more important now than ever. If today's award to Sargent and Sims has a political message, it is that.

But in the long run, I think it would be better if the Bank of Sweden adopted more stringent criteria for the awarding of the prize, more akin to the criteria for the Nobel in Medicine. That may mean fewer winners - perhaps only one a year, or even some years of "no recipient." It will certainly tilt the award toward microeconomists. But so be it. If you're going to call it the "Prize in Economic Sciences," then my opinion is that you should back that up.

In the meantime, though, congratulations to today's winners. Three cheers for better macro empirics!

Kamis, 06 Oktober 2011

US Working Toward Standardized Penalties for Data Breaches

Last month the US Senate’s Judiciary Committee approved three bills that deal with data breaches.  Those three bills where, The Personal Data Privacy and Security Act of 2011, The Personal Data Protection and Breach Accountability Act of 2011 and the Data Breach Notification Act of 2011.  The gist of all these acts is that the government is working toward a standardized practice of requiring notification of data breaches and a standardization of penalties for companies that have data breaches.  What this means for business is that it is now very important for you to take as many precautions as you can to secure your clients’ private data.  Firewalls, antivirus software, IT consultants, encryptions, company internet usage policies and password protections are all key parts of securing your business for data breaches. 

Even if all the preventative measures are in place, your business still runs that risk of a data breach.  That is where insurance products can help protect your business.  Insurance products can’t help protect your data but they can protect your company’s money by helping pay for data breach notification costs, third party lawsuits filed against your company for breach of client’s personal information and the cost to restore lost data.

As the government moves to a more standardized notification requirement and penalties for data breaches, companies that hold private information should also be working toward setting up strong data security measures as well as put in place insurance products to help protect their company’s hard earned money.

Selasa, 04 Oktober 2011

Baxter & King 1993: Why government spending isn't just moving money around


This is the first in a series of posts called "Papers You Should Know". I believe one of the essential roles of econ blogs should be to bring research into the public consciousness. There's a ton of really interesting papers out there that get mooted in academic circles, or taught in grad classes, but whose insights never really make it into the wider discussion. That's a shame. It means that most intelligent, educated non-economists encounter a hundred worthless American Enterprise Institute hackonomics propaganda pieces for every one serious piece of scholarly research. Which, I find, often leaves people with the vague notion that academic economists spend 90% of their time glorifying the frictionless perfection of the free market, and the other 10% collecting "consulting" fees for big banks.

It isn't so. There is absolutely tons of research out there that looks at questions of how markets break down, and how complex "frictions" make interesting stuff happen. Today I'm going to look at one such paper: Marianne Baxter and Robert G. King's "Fiscal Policy in General Equilibrium" (American Economic Review, 1993).

First, for some background. One of the biggest questions for macroeconomists right now is whether government spending can boost the economy. You often hear conservative-minded economists saying that no, government spending is just "moving money around" without creating any wealth. For example, here is John Cochrane, of the University of Chicago, from 2009:

[M]oney [spent by the government] has to come from somewhere. If the government borrows a dollar from you, that is a dollar that you do not spend, or that you do not lend to a company to spend on new investment. Every dollar of increased government spending must correspond to one less dollar of private spending. Jobs created by stimulus spending are offset by jobs lost from the decline in private spending.

Where this idea really comes from is an academic paper - in fact, one of the most famous econ papers ever written. In "Are Government Bonds Net Wealth?" (Journal of Political Economy, 1974), Robert Barro (currently of Harvard) showed that under certain conditions, the timing of government spending doesn't matter for the economy. This idea, which is called "Ricardian Equivalence", is exactly what John Cochrane was talking about. In this model, government can only move economic activity around, not create it.

When I read this famous paper, I immediately found it fishy. One of the model's (unstated) assumptions is that government spending consists entirely of transfer payments - i.e., taking money from one person and handing it to another. In other words, Barro assumes that government is fundamentally different from, say, a corporation; while a corporation can invest money today to create new wealth tomorrow, government can only shuffle money around. There is no "government capital" that we can invest in today that will create new wealth down the road.

To me, this felt a bit like assuming the conclusion. If you just assume government doesn't produce anything new, of course it's going to be hard to get government spending to boost the economy! If you think that public goods can boost the economy, then everything changes. I pointed this out in a blog post back in March, and even considered writing a paper about it. Then I found out that someone had already written that paper. And those someones were Marianne Baxter and Robert G. King, in 1993.

Only scooped by 18 years. Not bad, eh?

What Baxter and King (here's the link again) do is to take your most basic neoclassical business cycle model - the RBC model - and simply add government capital. What is government capital? Well, it's any kind of capital that the private sector can't or won't build (or can't or won't build enough of). In other words, government capital is a nonrival production input, or "public good." For the math on how those work, see here. Basically, these are things like roads, electrical grids, airports, and other infrastructure. Schools and research centers and courts and police could also count.

So Baxter & King put public goods into the production function. Instead of only including private capital and labor, GDP now depends on government capital as well. Here's the equation, for those of you who like equations:


Everything else is just pure RBC - no frictions, no sticky prices, no sticky wages, no financial sector, no nuthin'. Exactly the way Ed Prescott would like it, except for that little KG thing there on the end.

And of course, what happens? "Ricardian equivalence" goes straight out the window! If the government can invest in useful projects just like a firm, then the timing of government spending matters a lot, just like the timing of private investment. Baxter & King find that, in their model, government spending has a huge "multiplier", even with none of the Keynesian stuff like sticky wages.

But this is hardly surprising. Like I said, Barro starts with the assumption that government spending is 100% transfers. It's almost painfully obvious that if you allow for government to actually build useful things, you're going to get a very different result. In fact, while giving full props to Baxter & King, I'm a little surprised it took until 1993 for people to do this.

So, do the data support Baxter-King? Well, the short answer is that I need to look into this a lot more. But here is an interesting paper by Michigan's own Rudi Bachmann, along with Eric Sims of Notre Dame, that shows that when the government invests more money, especially during downturns, it raises business confidence. The last line from the abstract basically says it all:
In particular, spending shocks during downturns predict future productivity improvements through a persistent increase in government investment relative to consumption, which is in turn reflected in higher measured confidence.
Which is exactly what you'd expect from Baxter-King.

Now let's return to the present debate over government spending. Most of that debate revolves around things like liquidity traps, sticky wages, business confidence, and so on. But if we live in a Baxter-King world (or a Bachmann-Sims world), the case for more spending is actually a lot simpler. We desperately need to repair our country's infrastructure. Only government will do that. Interest rates are historically low, meaning that now is the perfect time to borrow money to rebuild the roads. Doing so would raise employment today, but because roads are necessary for tomorrow's businesses to thrive, it would also raise GDP in the future. It's not just a slam dunk, it's a free lunch!

There is, of course, a caveat here. Government capital has its limits. As Japan proved when it concreted over its rivers and built bridges to nowhere in the 1990s, you can reach a point where more infrastructure is just inefficient (something that Baxter & King, notably, do not allow for in their model). But I would argue that, given the dilapidated, crumbling nature of America's roads and bridges, we are not anywhere near that point. 

So to sum up: Baxter & King (1993) show that it's very easy to get government spending to matter in a big way. All you have to do is assume that public goods exist. Every time you hear someone say that "the money [for stimulus] has to come from somewhere!", just tell them that the money will come from the future wealth that private businesses will create once they can ship goods to each other over our shiny, new, government-built roads. Or just say "Baxter & King, 1993".

Minggu, 02 Oktober 2011

"Industrial Complexes" and the Great Relocation


Paul Krugman created the theory that inspired my Great Relocation idea, so perhaps it's natural for him to invoke it regarding Congress' latest attempt to get tough on China's currency policy. But in any case, I am really glad to see him bring it up:

I though I should offer a brief note about one of the arguments people make against focusing on Chinese currency manipulation — namely, the claim that China doesn’t really compete head to head with US manufacturing, so that a rise in the renminbi wouldn’t help. 
I’d argue that this is wrong... 
[T]here are real effects on the US if production moves, say, from China to Mexico. To an important extent, global manufacturing is carried out by regional complexes — an Asian complex centered on Japan and China in effect competes with a North American complex in which labor-intensive stuff is done in Mexico or Central America. So there’s an indirect competitive effect.
This is exactly the Great Relocation story. An "industrial complex" is a cluster of suppliers that represent different levels in a value chain. Transport costs, broadly defined - including costs from the necessity for face-to-face contact with customers, the ability to hire people away from one's competitors, and local knowledge spillovers - are minimized when all the firms locate close to one another. This is what creates industrial clusters.

Look around the world, and you will see that industries tend to cluster. Electronics is centered in East Asia. Business services and software are centered in India and on the U.S. West Coast. Finance is in Britain and on the U.S. East Coast. Heavy industry is in Germany. Not exclusively, obviously, but the clusters are real.

These clusters raise productivity, by minimizing (broadly defined) transport costs. If I am a builder of televisions, it makes sense to locate in Japan or Korea, because there I will be close to many high-quality television parts suppliers. And it also makes sense for me to locate in Korea or Japan, because the existing cluster of TV manufacturing in that region provides me with a pool of knowledgeable employees to hire away from my competitors. And even if I don't hire them away from my competitors, they will meet my own employees in bars, and at trade associations, and socially, and they will exchange ideas (read Annalee Saxenian's Regional Advantage to find out why this was important in the development of Silicon Valley). All of those things increase both my productivity, the productivity of my suppliers and customers, and even the productivity of my competitors. In other words, the entire cluster gets a productivity boost from being a cluster. And high-productivity firms defeat low-productivity firms.

So what Krugman is saying is that the Chinese currency policy is holding Latin America back from developing its own industrial clusters. And that is indirectly holding back American manufacturing, because Latin American clusters are going to have more exchanges of products, ideas and people with the U.S. than clusters in East Asia.

Which is why one way of fighting the Great Relocation is to fight China's currency policy. Natural forces will eventually make densely-populated East Asia the world's high-tech biggest manufacturing hub. But there is no reason we should let Chinese government policy speed up that transition.